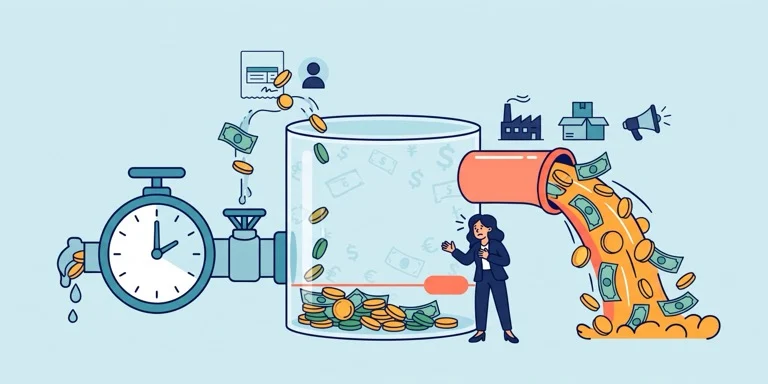
For many entrepreneurs and small business owners, the milestone of recording a record-breaking month of sales is a moment for celebration. Order volumes spike, products move swiftly off shelves, and revenue charts trend sharply upward. Yet, a severe financial reality often shatters this early triumph: when a major supplier invoice arrives, the business bank account is entirely unable to cover it.
Contrary to popular belief, severe cash flow crises are not exclusively the domain of failing enterprises or businesses nearing bankruptcy. In fact, some of the most acute liquidity crunches routinely afflict companies that are scaling rapidly and posting healthy profits on paper. This phenomenon highlights a fundamental misunderstanding in modern commerce—the dangerous gap between earning revenue and actually possessing liquid cash.
Understanding the Mechanics of Revenue Versus Cash Flow
The primary point of confusion for many emerging enterprises lies in the divergent timelines of accounting revenue and actual cash realization. In standard bookkeeping practices, revenue is formally recorded the exact moment a transaction or sale is completed. However, the physical or electronic currency associated with that transaction rarely appears in a company’s bank account simultaneously.
For instance, a business might successfully fulfill and ship a large commercial order in January. Operating under standard business-to-business conventions, the customer is extended thirty-day payment terms, meaning the funds will not clear until February. Financial statements accurately reflect January revenue, but the company’s immediate bank balance remains entirely unaffected until the following month. When this dynamic is multiplied across hundreds of transactions, each operating on disparate payment schedules, a massive disconnect emerges between a company’s reported financial performance and its immediate liquidity.
Financial analysts emphasize that neither reporting metric is inaccurate; rather, they measure entirely different variables. While income statements track economic activity and obligations over a specific temporal window, bank accounts reflect pure, unencumbered liquidity available to settle immediate liabilities.
The Illusion of Paper Profitability
This temporal disconnect explains why asking the standard question—"Are we profitable?"—can provide a false sense of security for business leaders. Profitability is fundamentally an accounting calculation derived by subtracting total operational costs from total revenue over a defined fiscal period.
A business can easily generate a robust, positive profit margin for a given quarter while simultaneously watching its operational bank account scrape dangerously close to zero. Profit calculations operate independently of cash timing, whereas essential business expenses—such as monthly commercial rent, payroll, and tax obligations—demand immediate, liquid settlement.
Consider a retail enterprise experiencing a surge in demand for its flagship product. While this represents commercial success, fulfilling this demand requires purchasing raw materials and inventory upfront. The business must pay its suppliers immediately, while the newly manufactured inventory takes weeks to transit and months to sell through to end consumers. On paper, the enterprise appears exceptionally healthy and thriving. In reality, a substantial volume of liquid capital has left the business, trapped in inventory, and will not return until every unit is sold and the invoices are fully settled. The business is, effectively, profitable yet holding its breath.
Why Rapid Scaling Exacerbates Liquidity Pressures
Conventional business intuition suggests that rapid growth should naturally alleviate financial pressures. In practice, however, rapid scaling frequently triggers severe cash shortages.
Every incremental phase of business growth demands capital outlay long before it generates a return. Expanding sales require higher inventory procurement, larger manufacturing runs, and increased marketing expenditures to attract consumers. These financial commitments must be paid upfront or within tight credit windows, while customer receivables continue to trickle in according to delayed payment terms.
Consequently, the velocity of business expansion directly correlates with the capital a company must front at any given moment. The faster an enterprise grows, the wider the operational gap widens between outgoing expenditures and incoming receivables. This systemic flaw frequently catches ambitious founders off guard. A management team celebrating a historic quarter may actually be in a far more precarious financial position than a slower-growing competitor maintaining flat, predictable operations. Growth is inherently capital-intensive and must be funded with liquid cash reserves.
Industry Analysis and Expert Perspectives
Financial consultants and corporate restructuring experts frequently observe this trajectory in post-startup entities. According to commercial banking data, insufficient cash flow and premature scaling remain primary drivers behind small-to-medium enterprise (SME) closures, despite sustained market demand for their offerings.
"Entrepreneurs are routinely taught to obsess over top-line revenue growth and profit margins," explains corporate finance strategist Marcus Vance. "However, the operational graveyard is filled with companies that grew themselves out of business because they failed to synchronize the velocity of their cash conversion cycle with their operational expansion."
Industry watchdogs note that traditional accounting software has historically focused on historical reporting rather than predictive liquidity modeling. This lag leaves founders reacting to shortfalls after they materialize rather than anticipating them weeks in advance.
Chronology of a Cash Flow Crisis
To fully understand how profitable businesses encounter insolvency, financial historians and auditors track a standard chronological progression:
- Month One (The Sales Surge): The enterprise secures a major client contract or experiences a seasonal spike in consumer demand, resulting in record-high booking numbers and a surge in accounts receivable.
- Month Two (The Upfront Burden): To meet the increased demand, the company extends its credit lines, hires additional contract labor, and pays suppliers for raw materials. Cash reserves deplete rapidly.
- Month Three (The Waiting Period): Deliveries are completed, and formal invoices are dispatched with standard 30-to-60-day payment terms. On paper, the company’s valuation and revenue metrics look exceptional.
- Month Four (The Liquidity Wall): Fixed overhead costs, payroll, and tax obligations fall due simultaneously. Meanwhile, major clients delay payments or exercise the full length of their credit terms. The business faces a temporary default on essential liabilities despite being fundamentally profitable.
Strategic Solutions: Closing the Gap from Both Ends
Corporate finance experts assert that cash flow vulnerability is entirely manageable once leadership teams proactively address the timing discrepancy between receivables and payables. Mitigation strategies generally focus on two distinct operational pillars: acceleration of inflows and enhanced predictive visibility.
Accelerating Inflows
Every delayed or outstanding invoice represents company capital sitting idly in a client’s bank account. Establishing stringent credit controls is critical for growing enterprises. Best practices include issuing invoices immediately upon project completion, enforcing strict payment terms, offering seamless digital payment mechanisms, and aggressively following up on accounts nearing or past their due dates. While administrative discipline in accounts receivable lacks glamour, it remains one of the most effective levers a growing organization can pull to preserve liquidity.
Enhancing Financial Visibility
Beyond optimizing collection speeds, businesses must develop granular visibility into cash flow timing rather than relying solely on aggregate monthly totals. Management must track the exact chronology of incoming capital versus outgoing obligations.
Modern financial technology platforms, such as automated accounting and cloud-based financial management software like Xero, have transformed how growing businesses monitor their financial health. By centralizing invoicing, automated payment reminders, bank feeds, and real-time cash position dashboards into a single interface, these systems allow leadership to visualize cash trajectories well in advance. Identifying potential liquidity shortfalls weeks before they materialize transforms a crisis into a manageable planning exercise.
Broader Economic Implications
The systemic disconnect between revenue and cash flow carries significant implications for the broader economy. Small and medium-sized enterprises form the backbone of commercial supply chains and employment markets. When fundamentally viable companies experience sudden liquidity contractions, the ripple effects impact supplier networks, regional employment stability, and overall market velocity.
As economic conditions fluctuate and credit markets tighten, financial literacy regarding working capital management has transitioned from an administrative nice-to-have to a critical competency for corporate survival. Industry advocates continue to push for broader financial education for early-stage founders, emphasizing that understanding the nuances of cash conversion is just as vital as product-market fit.
Conclusion
Experiencing a liquidity squeeze is not an inherent indictment of a company’s business model or leadership capability. Countless successful enterprises have navigated the perilous waters of rapid growth only to find themselves blindsided by the divergent schedules of revenue recognition and cash realization.
By recognizing that a sale and its corresponding cash settlement are two distinct events, business leaders can fundamentally alter their operational posture. Treating payment collection as a primary growth lever, implementing rigorous accounts receivable protocols, and leveraging modern financial tracking tools enables companies to bridge the dangerous gap between earning and banking. Ultimately, mastering cash flow mechanics is the definitive mechanism that allows high-growth businesses to expand sustainably without holding their breath.